In this story
India’s middle class is growing, aspirations are rising, and the cost of living refuses to stand still. A child’s education that once cost a few lakhs can now demand several times more. A comfortable retirement, a home, or even a simple family wedding carries a much higher price tag than a decade ago. In this environment, merely saving money in a bank account or fixed deposit is no longer enough. You need to invest.
This guide is written specifically for Indian investors — salaried professionals, business owners, freelancers, and homemakers — who want practical, fact-based strategies rather than abstract theory. It covers why investing is essential, the major options available in India, real examples of how money grows, tax considerations under the current regimes, and common mistakes to avoid.
Why Investing Is Non-Negotiable for Indians
Retail inflation (CPI) stood at 5.5% in September 2026 and was widely expected to approach or touch the RBI’s 6% upper tolerance limit in October, driven largely by food prices and base effects. The RBI has projected inflation around 5.2% for 2026-27, with food inflation remaining a persistent pressure. Even if overall inflation moderates, the real cost of education, healthcare, and housing has risen faster for most families.
If your money earns less than inflation after tax, you are becoming poorer in real terms every year. A fixed deposit yielding 7% may look safe, but after tax (especially in higher slabs) and inflation, the real return can shrink to 1–2% or less. Equity-oriented investments have historically delivered higher long-term returns, though with volatility.
The power of compounding is the strongest ally an Indian investor has. Consistent, long-term investing turns modest monthly amounts into substantial corpora. This is why Systematic Investment Plans (SIPs) in mutual funds have become one of the most popular tools for ordinary Indians.
The Core Building Blocks of an Indian Investment Portfolio
A balanced approach usually combines growth assets (equity), safety assets (debt and government schemes), and some inflation hedges (gold). Here are the practical options most relevant in 2026:
1. Equity Mutual Funds via SIPs
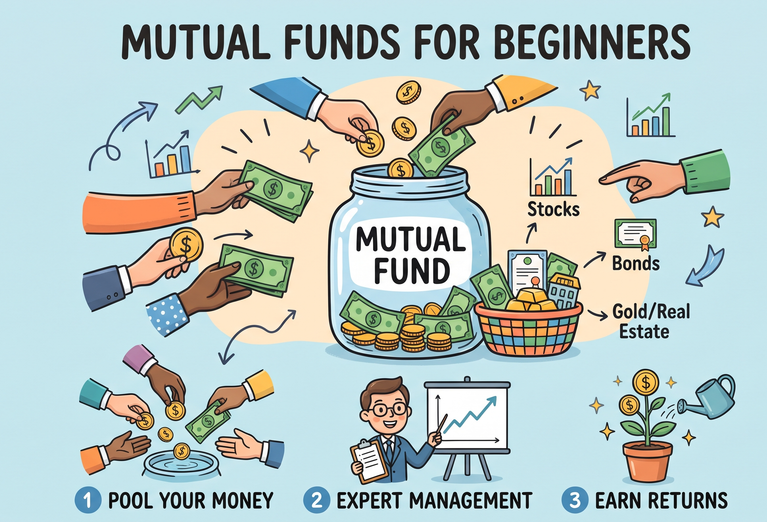
Equity mutual funds, especially through SIPs, remain one of the most effective wealth-creation tools available to retail investors. Historical 10-year SIP returns for many mid-cap and small-cap funds have exceeded 20% annualised in top-performing schemes. For example, certain small-cap funds turned a ₹10,000 monthly SIP into over ₹35–38 lakh over 10 years (total investment ₹12 lakh). Diversified categories such as flexi-cap, large & mid-cap, and multi-cap have also delivered strong long-term results, typically in the mid-to-high teens.
Large-cap and index funds offer relatively lower volatility and still beat inflation comfortably over long periods. Mid- and small-cap funds offer higher growth potential but come with sharper drawdowns. Most financial planners recommend a mix based on age and risk appetite: higher equity allocation when young, gradually shifting toward debt as retirement approaches.
Practical example: A 30-year-old starting a ₹10,000 monthly SIP in a diversified equity fund earning an average 12–14% CAGR over 25 years can accumulate a corpus well into crores, assuming continued contributions and reasonable market returns. Even at a more conservative 12%, the numbers become life-changing.
2. Public Provident Fund (PPF)
PPF currently offers 7.1% interest (reviewed quarterly), fully tax-free under the EEE (Exempt-Exempt-Exempt) status. The annual limit is ₹1.5 lakh, and the lock-in is 15 years (with partial withdrawals allowed later). It is one of the safest government-backed options and works especially well for conservative investors or as the debt/safety portion of a portfolio.
3. National Pension System (NPS)
NPS offers market-linked returns with the ability to choose equity, corporate debt, and government securities. Under the old tax regime, contributions qualify for the regular 80C/Section 123 limit plus an additional ₹50,000 under the equivalent of the old 80CCD(1B). At maturity, 60% of the corpus can be withdrawn tax-free, while 40% must be used to purchase an annuity (taxable as income). It is particularly useful for retirement planning.
4. Equity Linked Savings Scheme (ELSS)
ELSS funds have the shortest lock-in among tax-saving equity options — just three years. They invest primarily in equities and have historically delivered higher returns than traditional 80C instruments, though returns are market-linked. Long-term capital gains above ₹1.25 lakh are taxed at 12.5%. ELSS is suitable for investors who can tolerate equity volatility and want tax benefits under the old regime.
5. Other Useful Options
- Index funds / ETFs: Low-cost ways to track Nifty 50 or Sensex. As of mid-November 2026, the Nifty 50 was around 25,255 and the Sensex near 81,879 after a strong recovery rally.
- Sovereign Gold Bonds (SGBs): Offer gold price appreciation plus a small interest component, with tax benefits on maturity in many cases.
- Debt funds and liquid funds: Useful for short-term goals and emergency funds.
- EPF / VPF: For salaried employees, these remain excellent automatic savings vehicles.
Tax Efficiency Matters — Old vs New Regime
Under the current framework (Income-tax Act, 2025), the new tax regime is the default and generally does not allow the classic 80C-style deductions (now mapped under Section 123). The old regime still permits deductions up to ₹1.5 lakh under Section 123 for PPF, ELSS, EPF, NSC, life insurance premiums, tuition fees, home loan principal, etc., plus the extra ₹50,000 for NPS.
Many middle- and higher-income earners still find the old regime beneficial if they maximise deductions (especially those with home loans or significant NPS contributions). Others prefer the new regime’s simpler slabs and higher basic exemption/rebate structure. The right choice depends on your total deductions, salary structure (HRA, etc.), and income level. Run the numbers for both regimes before deciding.
Real-Life Allocation Examples
Young professional (age 28–35, moderate risk):
- 60–70% equity mutual funds / index funds via SIP
- 15–20% PPF or EPF
- 10–15% NPS
- Small allocation to gold or liquid funds for emergency buffer
Mid-career (age 40–50):
- 50–60% equity (more large-cap and flexi-cap tilt)
- Higher allocation to PPF / debt
- Maximise NPS for the extra deduction if using old regime
- Review home loan tax benefits if applicable
Conservative / near-retirement:
- Higher weight to PPF, SCSS (for seniors), debt funds, and limited equity exposure
- Focus on capital protection and regular income
Common Mistakes Indian Investors Make
- Stopping SIPs during market falls — This is the opposite of what works. Volatility is the price of higher long-term returns.
- Chasing last year’s top performers — Past returns do not guarantee future results. Consistency and asset allocation matter more.
- Ignoring asset allocation — Putting everything in equity or everything in FDs both create problems.
- Not reviewing the tax regime annually — The optimal choice can change with income, deductions, or life events.
- Treating real estate as the only “safe” investment — Illiquidity, high transaction costs, and maintenance often make it less efficient than a diversified financial portfolio for many goals.
- Delaying the start — Time in the market beats timing the market. Starting early with small amounts beats waiting for the “perfect” moment.
Practical Steps to Begin or Improve Your Investing
- Define clear goals with time horizons (short-term emergency fund, medium-term house/education, long-term retirement).
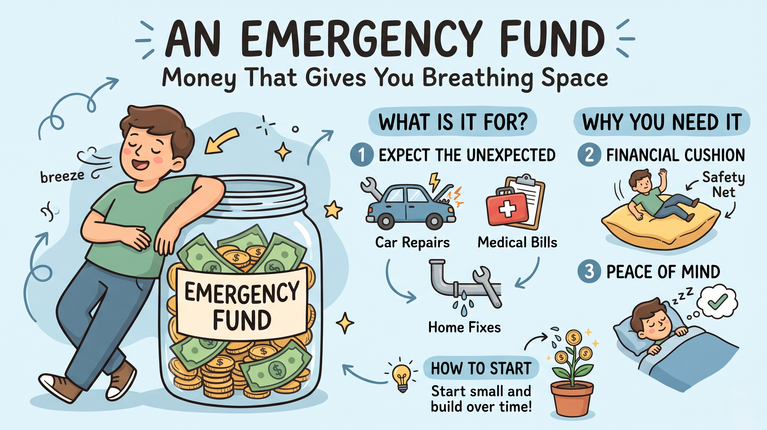
- Build an emergency fund of 6–12 months’ expenses in liquid instruments first.
- Start or increase SIPs in a mix of equity funds suited to your risk profile. Even ₹5,000–10,000 per month compounds powerfully over time.
- Maximise tax-efficient options (PPF, NPS, ELSS) according to the regime you choose.
- Review your portfolio once a year — rebalance if equity has grown far beyond your target allocation.
- Prefer direct plans of mutual funds to keep costs low.
- Use reliable platforms or a fee-only advisor if you need personalised guidance.
Final Thought
Investing successfully in India is less about finding secret tips and more about consistent behaviour: saving regularly, staying invested through market cycles, keeping costs low, and aligning investments with real life goals. Inflation will continue to erode the value of idle cash. Markets will rise and fall. The investors who treat investing as a long-term habit rather than a short-term gamble are the ones who build genuine financial security.
Start where you are. Increase contributions as income grows. Stay disciplined. Over 10, 15, or 25 years, the difference between investing and not investing becomes the difference between financial stress and financial freedom.
(This article is for educational purposes only and does not constitute personalised investment advice. Markets involve risk, and past performance is not indicative of future results. Consult a qualified advisor or do your own research before making investment decisions. Tax rules are subject to change; verify the latest provisions for your situation.)
Smart Investing for Indians in 2026: Build Real Wealth That Beats Inflation
India’s middle class is growing, aspirations are rising, and the cost of living refuses to stand still. A child’s education that once cost a few lakhs can now demand several times more. A comfortable retirement, a home, or even a simple family wedding carries a much higher price tag than a decade ago. In this environment, merely saving money in a bank account or fixed deposit is no longer enough. You need to invest.
This guide is written specifically for Indian investors — salaried professionals, business owners, freelancers, and homemakers — who want practical, fact-based strategies rather than abstract theory. It covers why investing is essential, the major options available in India, real examples of how money grows, tax considerations under the current regimes, and common mistakes to avoid.
Why Investing Is Non-Negotiable for Indians
Retail inflation (CPI) stood at 5.5% in September 2026 and was widely expected to approach or touch the RBI’s 6% upper tolerance limit in October, driven largely by food prices and base effects. The RBI has projected inflation around 5.2% for 2026-27, with food inflation remaining a persistent pressure. Even if overall inflation moderates, the real cost of education, healthcare, and housing has risen faster for most families.
If your money earns less than inflation after tax, you are becoming poorer in real terms every year. A fixed deposit yielding 7% may look safe, but after tax (especially in higher slabs) and inflation, the real return can shrink to 1–2% or less. Equity-oriented investments have historically delivered higher long-term returns, though with volatility.
The power of compounding is the strongest ally an Indian investor has. Consistent, long-term investing turns modest monthly amounts into substantial corpora. This is why Systematic Investment Plans (SIPs) in mutual funds have become one of the most popular tools for ordinary Indians.
The Core Building Blocks of an Indian Investment Portfolio
A balanced approach usually combines growth assets (equity), safety assets (debt and government schemes), and some inflation hedges (gold). Here are the practical options most relevant in 2026:
1. Equity Mutual Funds via SIPs
Equity mutual funds, especially through SIPs, remain one of the most effective wealth-creation tools available to retail investors. Historical 10-year SIP returns for many mid-cap and small-cap funds have exceeded 20% annualised in top-performing schemes. For example, certain small-cap funds turned a ₹10,000 monthly SIP into over ₹35–38 lakh over 10 years (total investment ₹12 lakh). Diversified categories such as flexi-cap, large & mid-cap, and multi-cap have also delivered strong long-term results, typically in the mid-to-high teens.
Large-cap and index funds offer relatively lower volatility and still beat inflation comfortably over long periods. Mid- and small-cap funds offer higher growth potential but come with sharper drawdowns. Most financial planners recommend a mix based on age and risk appetite: higher equity allocation when young, gradually shifting toward debt as retirement approaches.
Practical example: A 30-year-old starting a ₹10,000 monthly SIP in a diversified equity fund earning an average 12–14% CAGR over 25 years can accumulate a corpus well into crores, assuming continued contributions and reasonable market returns. Even at a more conservative 12%, the numbers become life-changing.
2. Public Provident Fund (PPF)
PPF currently offers 7.1% interest (reviewed quarterly), fully tax-free under the EEE (Exempt-Exempt-Exempt) status. The annual limit is ₹1.5 lakh, and the lock-in is 15 years (with partial withdrawals allowed later). It is one of the safest government-backed options and works especially well for conservative investors or as the debt/safety portion of a portfolio.
3. National Pension System (NPS)
NPS offers market-linked returns with the ability to choose equity, corporate debt, and government securities. Under the old tax regime, contributions qualify for the regular 80C/Section 123 limit plus an additional ₹50,000 under the equivalent of the old 80CCD(1B). At maturity, 60% of the corpus can be withdrawn tax-free, while 40% must be used to purchase an annuity (taxable as income). It is particularly useful for retirement planning.
4. Equity Linked Savings Scheme (ELSS)
ELSS funds have the shortest lock-in among tax-saving equity options — just three years. They invest primarily in equities and have historically delivered higher returns than traditional 80C instruments, though returns are market-linked. Long-term capital gains above ₹1.25 lakh are taxed at 12.5%. ELSS is suitable for investors who can tolerate equity volatility and want tax benefits under the old regime.
5. Other Useful Options
- Index funds / ETFs: Low-cost ways to track Nifty 50 or Sensex. As of mid-November 2026, the Nifty 50 was around 25,255 and the Sensex near 81,879 after a strong recovery rally.
- Sovereign Gold Bonds (SGBs): Offer gold price appreciation plus a small interest component, with tax benefits on maturity in many cases.
- Debt funds and liquid funds: Useful for short-term goals and emergency funds.
- EPF / VPF: For salaried employees, these remain excellent automatic savings vehicles.
Tax Efficiency Matters — Old vs New Regime
Under the current framework (Income-tax Act, 2025), the new tax regime is the default and generally does not allow the classic 80C-style deductions (now mapped under Section 123). The old regime still permits deductions up to ₹1.5 lakh under Section 123 for PPF, ELSS, EPF, NSC, life insurance premiums, tuition fees, home loan principal, etc., plus the extra ₹50,000 for NPS.
Many middle- and higher-income earners still find the old regime beneficial if they maximise deductions (especially those with home loans or significant NPS contributions). Others prefer the new regime’s simpler slabs and higher basic exemption/rebate structure. The right choice depends on your total deductions, salary structure (HRA, etc.), and income level. Run the numbers for both regimes before deciding.
Real-Life Allocation Examples
Young professional (age 28–35, moderate risk):
- 60–70% equity mutual funds / index funds via SIP
- 15–20% PPF or EPF
- 10–15% NPS
- Small allocation to gold or liquid funds for emergency buffer
Mid-career (age 40–50):
- 50–60% equity (more large-cap and flexi-cap tilt)
- Higher allocation to PPF / debt
- Maximise NPS for the extra deduction if using old regime
- Review home loan tax benefits if applicable
Conservative / near-retirement:
- Higher weight to PPF, SCSS (for seniors), debt funds, and limited equity exposure
- Focus on capital protection and regular income
Common Mistakes Indian Investors Make
- Stopping SIPs during market falls — This is the opposite of what works. Volatility is the price of higher long-term returns.
- Chasing last year’s top performers — Past returns do not guarantee future results. Consistency and asset allocation matter more.
- Ignoring asset allocation — Putting everything in equity or everything in FDs both create problems.
- Not reviewing the tax regime annually — The optimal choice can change with income, deductions, or life events.
- Treating real estate as the only “safe” investment — Illiquidity, high transaction costs, and maintenance often make it less efficient than a diversified financial portfolio for many goals.
- Delaying the start — Time in the market beats timing the market. Starting early with small amounts beats waiting for the “perfect” moment.
Practical Steps to Begin or Improve Your Investing
- Define clear goals with time horizons (short-term emergency fund, medium-term house/education, long-term retirement).
- Build an emergency fund of 6–12 months’ expenses in liquid instruments first.
- Start or increase SIPs in a mix of equity funds suited to your risk profile. Even ₹5,000–10,000 per month compounds powerfully over time.
- Maximise tax-efficient options (PPF, NPS, ELSS) according to the regime you choose.
- Review your portfolio once a year — rebalance if equity has grown far beyond your target allocation.
- Prefer direct plans of mutual funds to keep costs low.
- Use reliable platforms or a fee-only advisor if you need personalised guidance.
Final Thought
Investing successfully in India is less about finding secret tips and more about consistent behaviour: saving regularly, staying invested through market cycles, keeping costs low, and aligning investments with real life goals. Inflation will continue to erode the value of idle cash. Markets will rise and fall. The investors who treat investing as a long-term habit rather than a short-term gamble are the ones who build genuine financial security.
Start where you are. Increase contributions as income grows. Stay disciplined. Over 10, 15, or 25 years, the difference between investing and not investing becomes the difference between financial stress and financial freedom.
(This article is for educational purposes only and does not constitute personalised investment advice. Markets involve risk, and past performance is not indicative of future results. Consult a qualified advisor or do your own research before making investment decisions. Tax rules are subject to change; verify the latest provisions for your situation.)