In this story
Your colleague has started a SIP. A cousin says an index fund is the easiest way to invest. An Instagram video promises to explain how a small monthly investment can turn into a huge retirement corpus.
Meanwhile, you are wondering something much simpler: “Where do I begin without making an expensive mistake?”
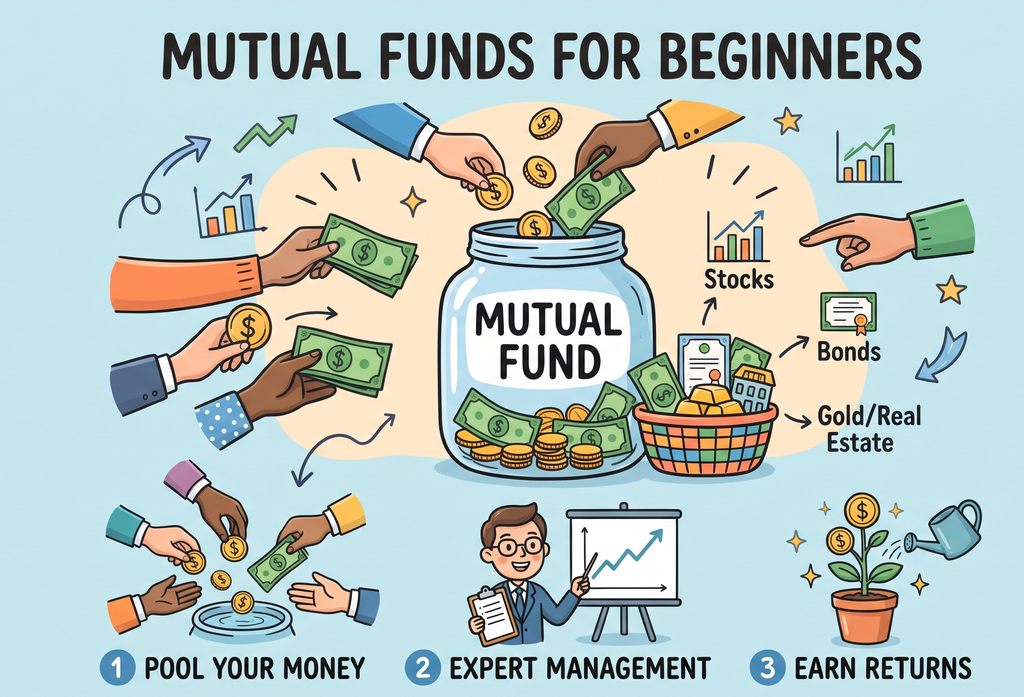
Begin here: a mutual fund pools money from many investors and invests it according to a defined strategy. You receive units representing your investment, and their value changes as the fund’s investments change. Professional management makes mutual funds accessible, but it does not make them risk-free or guarantee returns.investor.sebi.gov+1
You do not need to learn every financial term before starting. You do need to understand what you are buying, why you are buying it and when you might need the money.
1. What Is a Mutual Fund, in Plain English?
Imagine you want to invest, but you do not have the time or knowledge to choose individual shares or bonds.
A mutual fund gives you a way to invest in a portfolio managed under a stated investment objective. Depending on the scheme, that portfolio might hold company shares, debt securities or a combination of assets. An asset management company, or AMC, manages the scheme and charges expenses for running it.investor.sebi.gov+1
When you invest, you receive units.
The value per unit is called Net Asset Value, commonly shortened to NAV. Broadly, it represents the value of the fund’s assets after deducting its liabilities, divided by the number of units.investor.sebi.gov
Here is a simplified example, ignoring transaction-related adjustments:
- You invest ₹2,000.
- The applicable NAV is ₹50.
- You receive 40 units.
- If the NAV later becomes ₹55, those units are worth ₹2,200.
- If it falls to ₹45, they are worth ₹1,800.
That change in value is why a mutual fund should not be treated like an account with a promised return. Your investment can rise or fall.investor.sebi.gov
2. Start With Your Goal, Not a “Best Fund” List
Suppose Priya, a fictional 28-year-old working in Bhubaneswar, has three goals:
| Goal | When she needs the money | What she needs to think about |
|---|---|---|
| Paying a course fee | In eight months | Whether the money will be available when required |
| Saving towards a home deposit | In several years | How much uncertainty the goal can tolerate |
| Building retirement savings | Over decades | Long-term growth, risk and a sustainable contribution |
These are different jobs for money. They should not automatically lead to the same investment choice.
SEBI advises investors to assess a scheme’s suitability against their financial goals and ability to take risk, rather than choosing on performance alone.investor.sebi.gov
Before comparing funds, write one sentence:
“I am investing ₹_____ regularly for , and I expect to need the money in .”
Then ask a harder question: “What happens if this investment is worth less when I need it?”
That answer helps you judge suitability more honestly than asking only how much return you might earn.investor.sebi.gov
3. Understand the Main Types of Mutual Funds
“Mutual fund” is a broad label, not a single investment.
Equity funds
Equity funds invest primarily in company shares. Their value is exposed to stock-market movements, so professional management does not remove the possibility of losses.investor.sebi.gov+1
Before choosing one, consider whether you can tolerate fluctuations without being forced to sell to meet an essential expense.
Debt funds
Debt funds invest primarily in instruments such as government and corporate debt. They are different from equity funds, but they are still market-linked investments—not bank deposits with a promised return.investor.sebi.gov+1
Do not translate the word “debt” into “guaranteed safety.” Read the particular scheme’s documents and risk disclosures.
Hybrid funds
Hybrid funds combine equity and debt in varying proportions. The mix matters: two funds with the word “hybrid” in their names may expose you to different levels of risk. Examine the asset allocation rather than relying on the label alone.investor.sebi.gov+1
Index funds
An index fund seeks to track a specified market index rather than select investments with the aim of outperforming it. Its returns broadly follow that index, subject to expenses and tracking differences.investor.sebi.gov+1
This can make the strategy easier to understand, but “index” does not mean “safe.” The risk still depends on what the index contains.investor.sebi.gov+1
4. SIP Is How You Invest, Not What You Invest In
This is one of the most useful distinctions a beginner can learn.
A Systematic Investment Plan, or SIP, is a facility for investing periodically in a mutual fund. It is not a separate asset class or a promise of returns.investor.sebi.gov+1
You could use a SIP to invest in different kinds of schemes. The underlying scheme determines the investment exposure and risk—not the fact that you pay monthly.investor.sebi.gov+1
Think of it this way:
The mutual fund is what you buy. The SIP is the schedule you use to buy it.
What happens when prices change?
Consider this simplified illustration:
| Month | Investment | NAV | Units purchased |
|---|---|---|---|
| First month | ₹1,000 | ₹50 | 20 |
| Second month | ₹1,000 | ₹40 | 25 |
| Third month | ₹1,000 | ₹50 | 20 |
| Total | ₹3,000 | — | 65 |
The same contribution buys more units when the NAV is lower and fewer when it is higher. This is the principle behind rupee-cost averaging.investor.sebi.gov
However, accumulating more units during a fall does not guarantee that their value will recover by the time you need to sell. Mutual fund returns remain uncertain, whether you invest through a SIP or otherwise.investor.sebi.gov
A SIP can make investing more regular. It cannot make an unsuitable fund suitable.
5. Direct and Regular Plans: Know What You Are Paying For
You may see the same scheme offered as a direct plan and a regular plan.
The underlying portfolio is the same, but the cost structure differs. A regular plan includes distributor commissions within its expenses; a direct plan does not include those distribution commissions and therefore has a lower expense ratio. That cost difference affects returns over time.investor.sebi.gov
| Feature | Direct plan | Regular plan |
|---|---|---|
| Distribution commission within expenses | Not included | Included |
| Expense ratio for the same scheme | Lower | Higher |
| Distribution support | Not built into the plan | May be provided through the distributor |
Neither label changes the underlying portfolio into a safer investment. The central distinction is distribution and cost.investor.sebi.gov
If someone helps you invest, ask clearly:
- Are you recommending a direct or regular plan?
- How are you paid?
- What support will you provide?
- What will this investment cost me?
The aim is not to avoid all paid help. It is to understand the arrangement before agreeing to it.
6. Growth and IDCW: A Payout Is Not Free Extra Money
Another choice concerns what happens to income and gains within the scheme.
Under the growth option, gains are retained within the scheme and reflected in its NAV rather than distributed to you. Under a distribution option, payouts depend on distributable surplus; the NAV falls to reflect the distribution.investor.sebi.gov
You may encounter the label IDCW—Income Distribution cum Capital Withdrawal—for the distribution option. Do not confuse such a payout with guaranteed interest or an extra reward on top of an unchanged investment value.
SEBI’s explanation makes the important economic point: when a distribution is paid, the NAV reduces to reflect it.investor.sebi.gov
For beginners, the practical question is whether you are trying to accumulate money or receive distributions—and whether the option actually fits that purpose.
7. Understand Costs Before Looking at Returns
An attractive return figure is only part of the picture. SEBI advises investors to consider fees and taxes before investing.investor.sebi.gov
Expense ratio
This represents the ongoing expenses of operating the scheme. These costs affect the value available to investors, which is one reason the direct-versus-regular distinction matters.investor.sebi.gov+1
Compare costs between genuinely comparable options, rather than assuming every low-cost fund serves the same purpose.
Exit load
An exit load is a charge that may apply when you redeem units within a specified period. The conditions differ between schemes.investor.sebi.gov
For example, if an applicable exit load is 1% and the redemption value subject to that charge is ₹20,000, the charge would be ₹200.
Read the scheme’s actual terms. Do not assume every fund has a one-year exit-load period or that every redemption is free.investor.sebi.gov
Taxes
Tax treatment is another factor in what you ultimately keep. Check the rules applicable to the fund and your transaction when making a decision; do not treat the return shown on a screen as necessarily equal to your after-tax proceeds. SEBI specifically flags taxes as a consideration before investing.investor.sebi.gov
8. Read the Riskometer—and Then Look Further
The Riskometer is a standardised visual indication of a mutual fund scheme’s risk level. It helps investors compare the risk of the scheme with their own willingness and ability to bear it.investor.sebi.gov
It is a starting point, not a complete explanation.
Also examine:
- The scheme’s investment objective.
- The assets it holds.
- Whether its portfolio is concentrated.
- The costs and exit conditions.
- How its strategy fits your goal.
SEBI’s investor material recommends understanding the investment objective, assessing suitability and keeping track of the portfolio—not simply watching returns.investor.sebi.gov
A useful personal test is to imagine your ₹50,000 investment falling to ₹40,000. This is a hypothetical scenario, not a forecast.
Would you need to withdraw it for an essential payment? Would you feel compelled to sell? Those answers deserve attention before you invest, not only after markets fall.
9. Four Beginner Mistakes Worth Avoiding
Choosing last year’s winner
Past performance does not establish what a scheme will earn next. SEBI explicitly warns that historical returns are not indicative of future performance.investor.sebi.gov
Use performance as part of an assessment, not as a promise.
Believing a ₹10 NAV means a bargain
A lower NAV does not automatically make a fund cheaper or better. Likewise, a new fund offer at ₹10 is not necessarily a bargain compared with an existing scheme.investor.sebi.gov
The number of units you receive is less important than how your invested amount performs.
Assuming “monthly investment” means “monthly profit”
A SIP schedules contributions. It does not schedule gains. Your investment remains subject to market movements.investor.sebi.gov+1
Buying before understanding
If you cannot explain what the fund invests in, what could go wrong and why it suits your goal, pause. SEBI advises investors to examine suitability and avoid unrealistic or guaranteed-return expectations.investor.sebi.gov
There is no prize for making a financial decision before you understand it.
10. A Simple Checklist Before Your First Investment
Before pressing “invest,” make sure you can answer these questions:
- What goal is this money meant for?
- When might I need to withdraw it?
- What does the scheme invest in?
- What losses or fluctuations could I reasonably face?
- Is the plan direct or regular?
- Which option have I selected?
- What are the expense ratio and exit-load terms?
- Have I read the key scheme information rather than relying only on a sales message?
These checks reflect SEBI’s core guidance: understand the scheme, assess risk and suitability, account for costs, and avoid treating returns as guaranteed.investor.sebi.gov
You do not need an impressive-looking portfolio on day one. You need a decision you understand.
The Bottom Line: Begin With Purpose, Not Pressure
Mutual funds can provide access to professionally managed portfolios without requiring you to select every underlying investment yourself. But convenience and professional management do not remove market risk.investor.sebi.gov
So, before asking, “Which mutual fund should I buy?”, ask:
“What job does this money need to do—and can this investment do that job without exposing me to risks I cannot afford?”
That question may not sound as exciting as a promise of spectacular returns. It is a much stronger place to begin.
This article is for general financial education, not a recommendation to buy a particular scheme. All people and numerical scenarios are illustrative. Mutual fund investments are subject to market risks; read the scheme-related documents carefully.